Q3 2026 Global AI Venture Funding Sets Historic Record: $159B Raised, 27 Unicorn Rounds, $679B Cumulative Through First Three Quarters
Data Overview
According to the latest Crunchbase data, global venture funding in Q3 2026 reached $159 billion, setting a historic high. Even more remarkable, the cumulative funding total for the first three quarters of 2026 has reached $679 billion, far exceeding the full-year 2025 level.
In this funding boom, AI-related investments dominate, driving prosperity across the entire venture capital market.
Key Data Highlights
Record Unicorn Rounds
The most striking data point in Q3 2026 is the number of unicorn rounds (funding of $1 billion or more):
| Quarter | Number of Unicorn Rounds |
|---|---|
| Q1 2026 | 14 |
| Q2 2026 | 16 |
| Q3 2026 | 27 |
Q3's 27 unicorn rounds set a historical record, up 69% quarter-over-quarter, demonstrating continued high investor confidence in the AI sector.
Infrastructure Investment Dominates
In Q3 2026 funding, "physical AI" infrastructure dominated:
- Data Centers: Over $10 billion raised
- Semiconductors: Over $10 billion raised
- Robotics: Over $10 billion raised
Each of these three sectors raised over $10 billion, reflecting strong market demand for AI infrastructure.
Representative Funding Cases
PaleBlueDot AI: $200M Series C
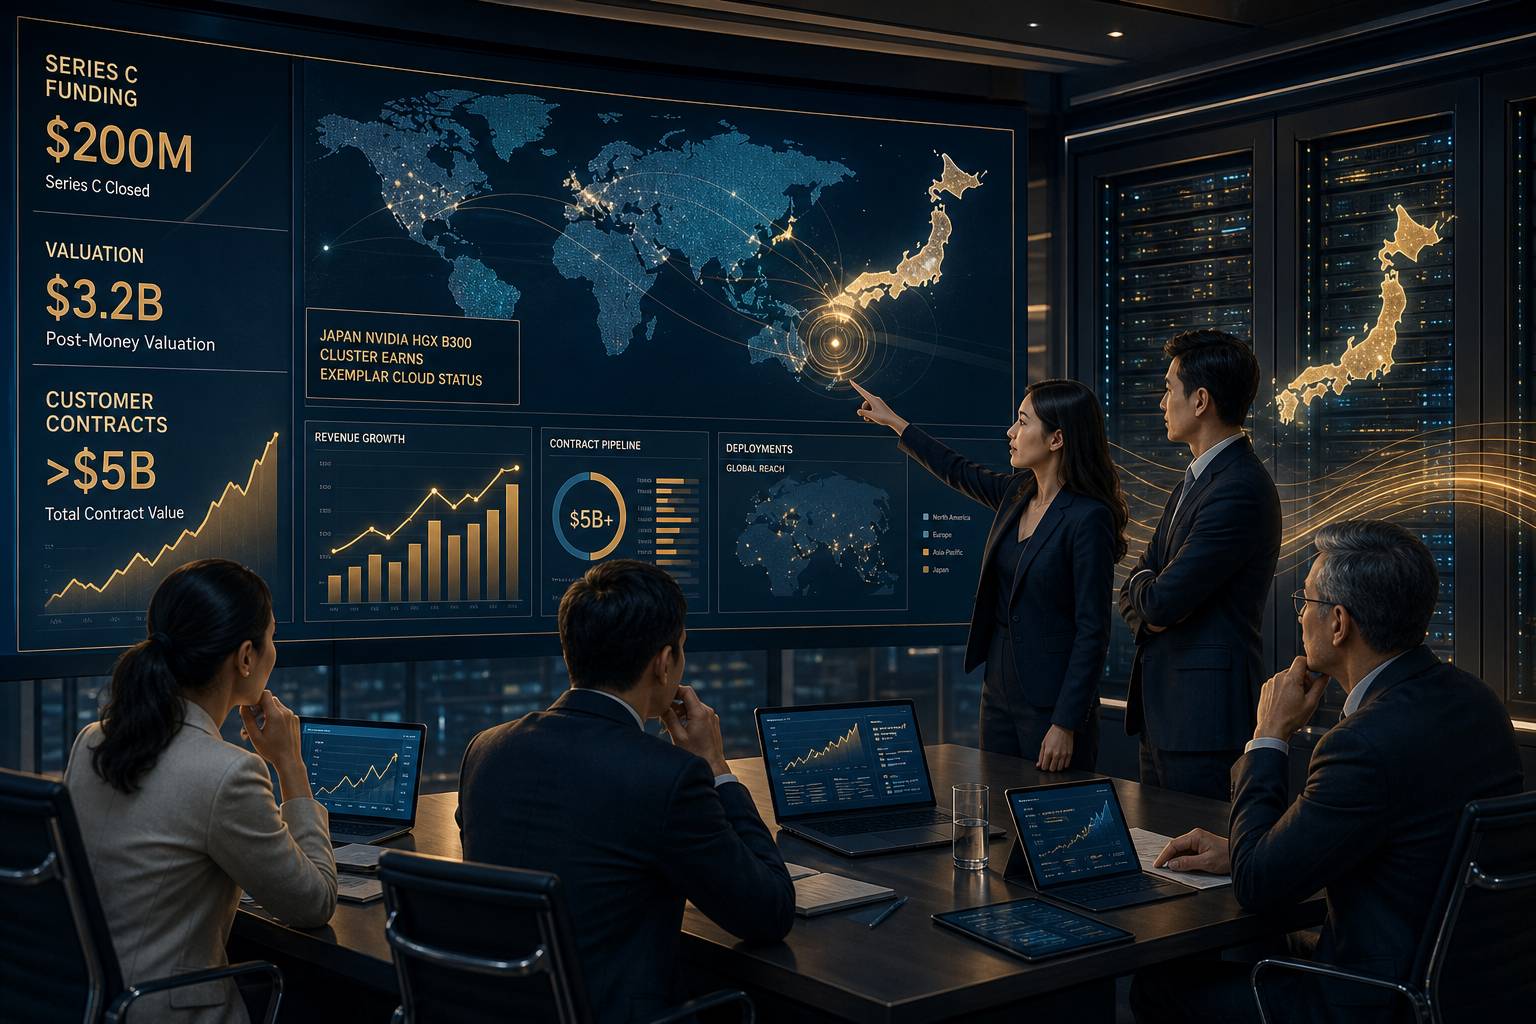
On October 1, 2026, Palo Alto-based PaleBlueDot AI completed a $200 million Series C round at a $3.2 billion valuation. The company operates GPU clusters and a compute marketplace, positioning itself as a critical infrastructure provider for frontier AI workloads.
PaleBlueDot AI's customer contracts have exceeded $5 billion, and its NVIDIA HGX B300 cluster deployed in Japan earned "Exemplar Cloud" certification, demonstrating strong positioning in the Asia-Pacific region.
DriveX: ~¥150 Million
Japanese AI startup DriveX secured approximately ¥150 million to expand its AI-driven factory production planning system. The system integrates into existing ERP/MES workflows to optimize manufacturing constraints, representing a typical case of the "applied AI" investment trend.
Gwanak Research Institute: ₩300 Million
South Korea's Gwanak Research Institute raised ₩300 million to deploy AI decision engines in the financial sector, focusing on normalizing unstructured data for banks and insurers.
Certo Aerospace: £5 Million
UK-based Certo Aerospace raised £5 million to advance its "Capstone" autonomous heavy-lift aircraft from prototype to repeatable manufacturing, marking accelerated commercialization of AI in aerospace.
Deep Analysis of Investment Trends
Trend 1: From General to Vertical Applications
The most significant investment trend in 2026 is the shift from general model investments to vertical application investments. Investors are moving away from broad "general intelligence" bets toward vertical applications that replace or compress specific expensive workflows.
DriveX (factory planning) and Gwanak Research Institute (financial decisioning) are typical representatives of this trend: they integrate AI into complex data environments specific to particular industries, creating competitive moats that are difficult to replicate.
Trend 2: Context as a Moat
Investors increasingly value "context moats" — the ability to integrate AI into proprietary, messy data environments (such as factory-specific constraints or internal financial records).
Such companies are considered more defensible than those relying solely on general-purpose APIs, because their competitive advantage comes from deep understanding of specific business contexts rather than the model's capabilities alone.
Trend 3: Infrastructure-Intensive Financing
The PaleBlueDot AI case demonstrates the financing characteristics of infrastructure-intensive business models: complex financial models that account for hardware depreciation, electricity costs, and supply-chain execution, rather than traditional software-only growth metrics.
The rise of this financing model reflects the special nature of AI infrastructure investment: high capital expenditure, long payback periods, but extremely high competitive barriers once scale advantages are established.
Trend 4: Efficiency Metrics Priority
Investors are increasingly prioritizing revenue-per-employee and capital efficiency over raw headcount growth. This is a response to the "trough of disillusionment" — many enterprises have yet to realize significant financial returns from AI investments.
In this context, AI companies that can achieve high revenue with lean teams receive higher valuation premiums.
Asia-Pacific Investment Landscape
Japan: Compute Infrastructure Hotspot
Japan is becoming an important destination for AI compute infrastructure investment in Asia-Pacific. PaleBlueDot AI's NVIDIA HGX B300 cluster deployed in Japan earned "Exemplar Cloud" certification, attracting large numbers of enterprise clients.
Japan's "AI Strategy 2026" provides substantial subsidies and tax incentives, further driving foreign AI infrastructure companies' investment in Japan.
South Korea: Financial AI Rising
South Korea's AI investment is concentrating on fintech and enterprise AI applications. The Gwanak Research Institute funding case reflects strong demand from Korean financial institutions for AI decision tools.
South Korea's Financial Supervisory Service (FSS) has issued a regulatory framework for AI applications in financial services, providing a clear compliance path for financial AI commercialization.
China: Open-Source Model Ecosystem
China's AI investment landscape differs, with more capital flowing into open-source model ecosystem development. The success of open-source models like Z.ai's GLM-5.2 is attracting more investor attention to Chinese AI infrastructure and toolchains.
Southeast Asia: Application Layer Opportunities
Southeast Asia's AI investment is primarily concentrated in the application layer, particularly in e-commerce, fintech, and healthcare. Singapore, as Southeast Asia's AI hub, has attracted regional headquarters and R&D centers from many multinational AI companies.
Market Risks and Challenges
Valuation Bubble Risk
The record 27 unicorn rounds has raised concerns among some analysts about valuation bubbles. In the AI boom, some companies may have received valuations disproportionate to their actual commercial value.
Return Realization Pressure
Despite massive funding volumes, many enterprise investors have yet to realize significant financial returns from AI investments. This "trough of disillusionment" may impact investment sentiment in coming quarters.
Geopolitical Risk
Intensifying US-China tech competition may affect cross-border AI investment and technology transfer. Asia-Pacific AI investors need to closely monitor the impact of geopolitical dynamics on the investment environment.
Outlook
The cumulative $679 billion in funding through the first three quarters of 2026 indicates that the AI investment boom is far from over. However, the market is moving toward greater maturity and rationality:
- Investors are paying more attention to commercial viability and profitability paths
- Vertical applications and infrastructure investments are replacing general models as mainstream
- Efficiency metrics and capital efficiency are receiving more attention
For Asia-Pacific AI entrepreneurs and investors, this trend means: AI companies with clear business models, deep industry integration, and strong data moats will have advantages in the future funding environment.
Frequently Asked Questions
Q: Is the Q3 2026 funding scale sustainable? A: Analysts are divided. Optimists believe long-term demand for AI infrastructure will support high funding levels; cautious observers worry that valuation bubbles and return realization pressure may lead to funding slowdowns.
Q: How does Asia-Pacific AI investment differ from global trends? A: Asia-Pacific AI investment is more diversified, ranging from Japan's compute infrastructure investments to South Korea's financial AI applications and Southeast Asia's consumer AI applications. Overall, Asia-Pacific investment volumes remain below North America but are growing faster.
Q: How can individual investors participate in the AI investment boom? A: Individual investors can participate by purchasing shares in AI-related listed companies, AI-themed ETFs, or through equity crowdfunding platforms for early-stage AI startups. However, the high-risk nature of AI investments should be noted, and diversification with thorough due diligence is recommended.
Q: What sectors within AI are attracting the most investment in 2026? A: The three largest sectors by investment volume are data centers, semiconductors, and robotics — each raising over $10 billion in Q3 2026 alone. At the application layer, healthcare AI, financial AI, and enterprise automation are attracting the most attention from venture investors.
Q: How does the 2026 AI investment cycle compare to previous tech investment cycles? A: The 2026 AI investment cycle is unprecedented in scale. The $679 billion raised in just three quarters exceeds the total venture funding for most previous years across all sectors. However, unlike the dot-com bubble, much of this investment is going into companies with real revenue and clear paths to profitability, suggesting a more sustainable cycle — though valuation risks remain.